
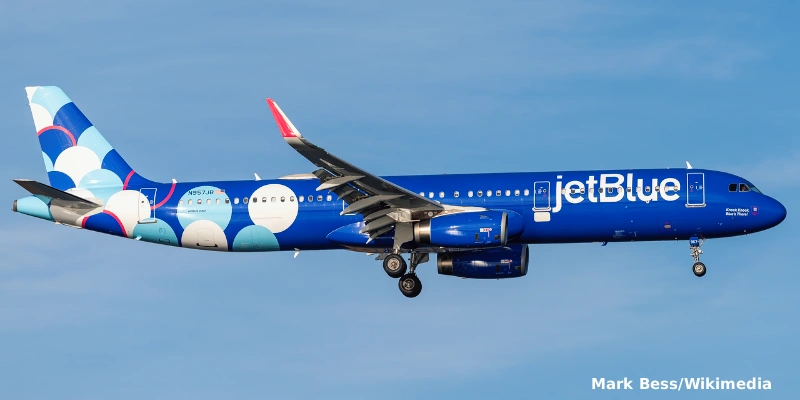
JetBlue Airways has categorically rejected entering talks with creditors or considering debt restructuring, seeking to quell Wall Street skepticism regarding the viability of its turnaround strategy in the wake of a steep plunge in its bond prices.
Executive Resolve Amid Debt-Holder Pressure
JetBlue Airways Chief Executive Officer Joanna Geraghty confirmed that the carrier is neither weighing financial restructuring nor engaging in negotiations with lenders. Her remarks follow reports that an ad hoc group of bondholders engaged advisory firms PJT Partners and Akin Gump—a standard precursor to debt renegotiations that rattled investor confidence.
“We are not in discussions with our creditors. Part of the point of today was to make clear that we are making progress on the underlying business,” Geraghty stated, underscoring that the carrier’s operational performance contrasts sharply with the pessimism seen in the secondary debt markets.
Additionally, the chief executive dismissed any intention to request U.S. government financial aid, despite meeting last week with U.S. Commerce Secretary Howard Lutnick to review broader industry issues.
Bond Market Turmoil and Maturity Schedule
Wall Street’s primary concern centers on whether the airline can finance its ongoing fleet and network overhaul without being forced to renegotiate its liabilities. JetBlue carries approximately $8.4 billion in total debt and finance lease obligations and has not posted an annual profit since 2019.
→ JetBlue Launches New Fort Lauderdale–Cali Route
Key debt metrics highlight the deteriorating market sentiment:
- Plunge in Bond Valuation: Roughly $2 billion in notes backed by its TrueBlue loyalty program fell to around 47 cents on the dollar as of October 26, after trading near 80 cents at the start of the month, according to London Stock Exchange Group (LSEG) data.
- Spike in Yields: The sell-off pushed yields north of 30%, a distressed level signaling significant credit risk regarding the airline’s repayment capabilities.
- Maturity Profile: Regulatory filings indicate that JetBlue faces $477 million in scheduled debt and lease maturities in 2027 and $582 million in 2028, leading up to a major maturity wall of $1.8 billion due in 2029.
Liquidity Position and Alternative Financing Options
Addressing the looming maturity profile, JetBlue management contends that its balance sheet provides sufficient runway to maintain uninterrupted operations for at least the next 12 months. At the close of September, the company reported $2.2 billion in total liquidity, alongside approximately $7.0 billion in unencumbered assets that could serve as collateral for additional credit facilities.
In the near term, the carrier expects to close a $250 million aircraft-backed financing facility in the fourth quarter. Looking further ahead, management has identified non-traditional monetization avenues beyond conventional debt:
- Its Paisly travel and booking platform.
- Venture fund investments and strategic stakes.
- Commercial partnership upside tied to its co-branded credit card portfolio.
Nevertheless, cash burn remains a challenge: JetBlue burned through $273 million in operating cash flow over the first nine months of 2026, up from $143 million used over the same period last year. Meanwhile, unrestricted cash, cash equivalents, and short-term investments contracted by nearly $850 million since December, landing at $1.6 billion by late September, driven in part by ongoing capital expenditures for aircraft deliveries.
Fuel Headwinds and Revised Operating Outlook
While third-quarter passenger revenue rose 21% year-over-year on resilient travel demand, a 61% surge in fuel expense effectively wiped out commercial gains. Consequently, net losses for the nine-month period nearly doubled, widening to $823 million.
This margin compression forced JetBlue to lower its full-year guidance. The carrier now projects an adjusted operating margin between -4.5% and -6.5%, weakening from the -2.0% to -5.0% range guided in July.
Despite high operating cost pressures, the airline remains committed to executing its standalone recovery plan outside bankruptcy court, targeting a return to operating profitability in 2027 and positive free cash flow generation by 2028.
Related Topics

Alaska Airlines to Connect Anchorage and Tokyo Narita with Nonstop Boeing 737 MAX Flights
Singapore Airlines Bolsters European Network with Launch of Madrid–Singapore Flights

Lufthansa Launches Nonstop Flights Between Frankfurt and Kuala Lumpur, Malaysia
Etihad Airways Touches Down in Thailand for First Time with Its Iconic Airbus A380

Plataforma Informativa de Aviación Comercial con 13 años de trayectoria.