Boeing Projects China’s Commercial Fleet Will More Than Double, Surpassing 9,800 Aircraft Over the Next 20 Years




China’s commercial aviation fleet is poised for a major operational shift and will more than double in size over the next two decades. The country’s passenger air traffic is projected to grow at an annual rate of 5%, driven by an expanding middle class, the addition of visa-free travel destinations, and sustained investment in aviation infrastructure.
Commercial Market Outlook 2026 Projections
According to Boeing’s 2026 Commercial Market Outlook (CMO) released in Beijing, the Chinese civil aviation sector will require 9,240 new aircraft between 2026 and 2045. Following rapid expansion over the past quarter-century, China currently operates the world’s second-largest commercial jet fleet at nearly 4,500 aircraft—a figure set to exceed 9,800 units in active service by 2045.
As the existing fleet matures, fleet renewal dynamics will strike a closer balance between network expansion and fleet modernization: 42% of deliveries over the 20-year horizon will replace older equipment with modern, more fuel-efficient models.
“Our long-term forecast continues to point to robust demand for new airplanes as China’s passenger traffic outpaces global growth, underpinned by sound economic and regulatory fundamentals that will make air travel increasingly accessible,” said Darren Hulst, Boeing Vice President of Commercial Marketing. “With a partnership spanning nearly 55 years, Boeing aircraft serve as the backbone of China’s civil aviation expansion, connecting people and moving cargo within and across continents.”
→ Boeing Unveils Dataliner: Next-Gen AI-Powered Aircraft Data Platform
Delivery Breakdown by Fleet Segment (2026–2045)
The Chinese domestic market will lead demand by volume. By 2045, China’s domestic air travel market is expected to solidify its position as the largest in the world, while the addition of more efficient narrowbody aircraft will broaden regional route networks into the Asia-Pacific and Central Asia regions.
Meanwhile, long-haul passenger traffic between China and Europe, North America, South America, Africa, and the Middle East will outstrip the broader regional average, driving heightened demand for widebody aircraft.
The 9,240 projected deliveries over the next 20 years break down across fleet categories as follows:
- Single-aisle aircraft: 7,215 deliveries (over 7,200 projected airframes, accounting for 78% of total national demand).
- Widebody aircraft: 1,460 deliveries (over 1,400 units dedicated to long-haul operations).
- Regional jets: 405 deliveries.
- Production freighters: 160 factory-built deliveries.
In air cargo, the intersection of large-scale manufacturing, advanced industrial development, and the world’s largest e-commerce market will generate total demand for 560 freighter aircraft—combining factory-built freighters and passenger-to-freighter (P2F) conversions—through 2045 to expand capacity and retire aging aircraft.
Commercial Services, Infrastructure, and Workforce Demand
This fleet expansion will necessitate a substantial scale-up across China’s technical aviation ecosystem:
- Commercial aviation services investment: Airlines in China will invest $875 billion over the next 20 years across digital solutions, aircraft maintenance, and technical personnel training to enhance operational capabilities and productivity.
- Aviation personnel demand: The civil aviation sector will require 425,000 new aviation personnel, comprising commercial pilots, maintenance technicians, and cabin crew. Supporting this growth will require specialized training pipelines structured around Competency-Based Training and Assessment (CBTA) methodologies, alongside the deployment of new flight and maintenance training centers.
Boeing has maintained an operational presence in China for more than 50 years, with local manufacturing facilities producing aerostructures and components across the 737, 767, 777, and 787 Dreamliner programs. The manufacturer’s footprint—encompassing supply chain integration, joint-venture revenues, commercial operations, flight training, and aerospace research and development—delivers a direct economic impact exceeding $1 billion, cementing China as a critical pillar of global commercial aviation over the next two decades.
Related Topics
Airbus Reaffirms Full-Year Guidance, Banking on Record Q4 Surge to Reach 870 Deliveries
Airbus and Air France-KLM Finalize Alpha Component Solutions Joint Venture for A350 Component Support
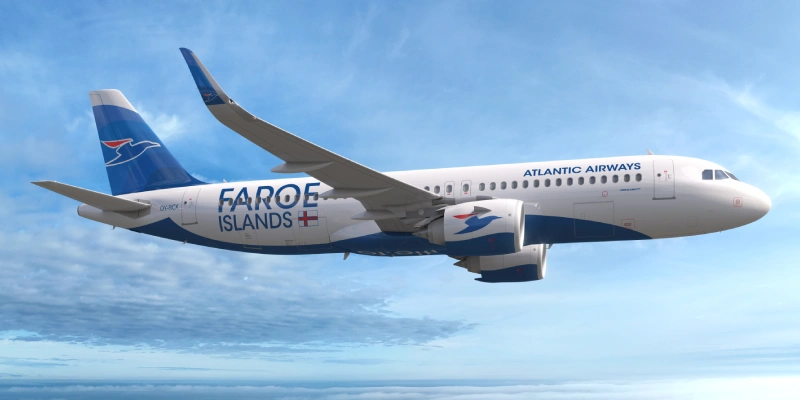
Atlantic Airways Orders Two Airbus A320neo Aircraft to Modernize Its Fleet
Allegiant Air Orders Six Additional Boeing 737 MAX Jets
Un apasionado por la aviación, Fundador y CEO de Aviación al Día.